Obsessed with tinkering with policy to lower prices, Europe doesn’t consider the system-level costs of transitioning to more expensive energy
Across
the European Union, factories are closing or quietly scaling back
production. Chemical plants, steel mills, fertilizer producers – the
most energy-intensive segments of the economy – are either relocating
abroad or shutting down altogether.
This is no temporary setback.
Europe has not emerged from the energy crisis of 2022 and it won’t
anytime soon. What is most alarming about this predicament is that
Europe’s leadership is unable to grasp what is happening to it.
Policymakers
are not oblivious to the loss of competitiveness but their approach to
confronting the problem is lodged in a misguided paradigm. They want to
bring energy prices down but give little thought to system-level costs.
Beholden to an abiding faith in the power of policy to overcome physical
constraints, they simply redistribute the burden of a declining energy
surplus through an elaborate display of policy legerdemain.
What Europe suffers from most of all is a profound, civilization-level energy illiteracy, which we will set out to explore.
A slow-motion self-sabotage
Slovak Prime Minister Robert Fico recently called the EU’s plan to completely phase out imports of Russian gas by next November “energy suicide.”
It’s remarkable that Europe has learned nothing from the past four
years and is charging full steam ahead down the same path. It’s also
particularly fitting that this suicide is so eagerly undertaken under
the misguided notion of countering an external adversary. The historian
Arnold Toynbee said that with few exceptions civilizations are not
killed but commit suicide.
But no civilization chooses the road
to perdition on purpose, and Europe remains to this day mostly content
with its rejection of Russian gas, while continuing to place its hopes
in the green energy transition even as it unravels before our eyes.
It
should come as no surprise that the period of peak optimism in the
energy transition – culminating in the Green New Deal (2019) – coincided
perfectly with the peak of Russian gas supplies to Europe (2018-19).
The ability of Germany, for example, to heavily subsidize its renewables
industry over the past two decades was predicated on the energy surplus
derived from availing itself of cheap Russian gas. In other words, the
prosperity required to dabble in renewables was squarely a function of
powering industry with cheap energy.
EU Commission President Ursula von der Leyen talks to the media in Brussels. February 1, 2023. © Thierry Monasse/Getty Images
When you have a Brussels-sized hammer, everything within reach is a nail
The Spanish philosopher Jose Ortega y Gasset distinguished between “ideas” and “beliefs.”
Ideas lie closer to the surface: we adopt them, debate them, apply
them, and discard them as needed. Beliefs, by contrast, are deeper and
less examined. They inhabit the dimly lit subterranean realms of our
being. We do not so much have them as inhabit them, and they quietly
shape the framework within which all our ideas are formed.
In
Europe’s case, chief among these beliefs is an unwavering faith in the
ability of administrative ingenuity to overcome physical limits. If only
the right policy mix can be found, the right subsidies provided, the
right collaboration undertaken, the right regulations enacted, then all
can be set aright – the physical reality be damned. Europe debates
policy (the ideas) but rarely the underlying assumptions (beliefs).
A corollary belief is that the decisive levers of economic life lie
not in physical realities or system-level costs but exclusively in the
realm of prices. Much modern economic theory, practically regardless of
school, coalesced during a time in which the energy component of
economic activity was hidden – not because it was insignificant but
because the energy cost of energy was low enough to not cause
distortions.
It is exactly these assumptions that have
underpinned Europe’s thinking about energy in recent decades. They
informed the thinking that plunged Europe into the crisis in the first
place and then shaped the response.
In 2022, wholesale prices
skyrocketed to more than €300 per megawatt hour (MWh), roughly ten times
the historical average. What followed was the deployment of a vast
administrative apparatus not to lower energy costs but to redistribute
them. Price caps were introduced on household electricity and gas, while
regulated tariffs were frozen. Governments also imposed windfall taxes
on utilities and oil and gas producers. Direct subsidies were provided
to compensate utilities and suppliers for losses created by those caps.
Then
came the LNG scramble. Floating LNG terminals were built, along with
new pipeline interconnections. Long-term LNG contracts were concluded at
significantly higher costs. LNG delivers lower net energy than pipeline
gas, while liquefaction, transport, and regasification are
energy-intensive processes. The switch to LNG has already cost the EU
tens of billions of euros upfront and that doesn't even count the higher
cost of the gas itself. Given that much of the infrastructure buildout
is funded through debt and public guarantees, and recovered through
network charges, the bill for this bonanza will be paid over the course
of decades.
The emergency measures were
of course improvised and implemented ad hoc, but they emerged entirely
from the beliefs discussed above. Four year later, the shock phase may
have ended – wholesale prices did later fall significantly – but the
crisis continues, and the playbook for confronting it is fundamentally
the same. Europe’s energy is now structurally more expensive, yet rather
than deal with this problem head on, policymakers continue to tinker
with the settings.
An LNG tanker anchored at a terminal. © Getty Images/Suphanat Khumsap
For example, Germany has proposed direct relief for its moribund industry by introducing a subsidized “industrial electricity price”
this year. At the EU level, Germany is also advocating that companies
be allowed to combine multiple electricity price-support mechanisms,
arguing that subsidies must be stacked. Italy has adopted a scheme
allowing industrial consumers to access electricity at a fixed price
well below recent national averages in exchange for commitments linked
to renewable energy. This is really only the tip of the iceberg.
This
sophisticated game of whack-a-mole does not lower system-level energy
costs; it merely redistributes them. The modern financial system and
sprawling administrative bureaucracies such as the EU are exceptionally
good at doing exactly that, namely obscuring physical reality by
shifting costs across time and redistributing losses. Prices tell us
what energy costs in financial terms, but not what it costs at the level
of the system, or the opportunity cost of diverting more economic
resources to obtain the same amount of more expensive energy.
In a system where financial capital is fungible, the real cost need
not appear in the prices of oil or gas themselves but can surface
elsewhere. US shale is a perfect example. Wellhead costs today may look
respectable, but they obscure the mountain of debt and infrastructure
required, not to mention all the distortions caused by artificially low
interest rates, to get there.
This dispersion is a feature of the
system, but it is also precisely what policymakers seek. Their goal is
to suppress the cost of the marginal unit (lower wholesale prices or
lower end-user prices) while allowing the real cost to dissolve into
complexity, where it becomes unmeasurable and politically safer.
It takes energy to obtain energy, money is just along for the ride
If
price signals are incomplete or distorted, and monetary costs are
distributed throughout the system and can be manipulated or obscured,
then not only do we have no idea what the true cost of energy is, we
lack a way to conceptualize it at all. Even if we could arrive at a
dollar figure, what would that number actually mean?
The
alternative is to conceive of energy not in monetary terms but in energy
terms. This sounds reasonable enough, but it already represents a
significant paradigm shift. It moves the discussion out of the realm of
paper claims – money and debt, which can be shuffled endlessly and
conjured out of nothing – and into the realm of the physical.
We
all understand that it takes energy to obtain energy. Drilling an oil
well, extracting the oil, transporting it, refining it, and storing it
are all energy-intensive processes. Energy is expended to obtain energy.
A
process that uses one joule of energy to obtain one joule of energy
produces no economic surplus. But the energy consumed in that process is
not always easy to trace. It may be pulled from the future through
debt, or distributed through a complex system of cost-bearing. What
matters is that no amount of financial engineering can change the
underlying energy balance. Either surplus energy is produced, or it is
not.
Drone view of an oil or gas drill fracking rig pad. © Getty Images/Joey Ingelhart
When energy becomes more
expensive, we are accustomed to looking for the difference only in
prices. But to conceptualize the true extent of the problem, we have to
look beyond prices.
The real question is what Europe must now
expend more of, for example, to obtain LNG from the US instead of
pipeline gas from Russia. The answer is: more economic resources,
masquerading as mere money, have to be diverted. But here we
mean economic resources, not financial resources (which would put us
back into the world of paper claims). We’re talking about real output –
or the capacity for it. That capacity, in turn, is ultimately a function
of applied energy and is constrained by how much surplus energy is
available. Germany’s deindustrialization points unmistakably in this
direction.
At a system level, when obtaining energy absorbs a
rising share of surplus energy, less remains for everything else. The
real cost of energy is therefore measured in energy itself. The relevant
concept is ECoE (energy cost of energy), a metric used by
energy-focused analysts
precisely because it captures something real even if it cannot be
calculated. More expensive energy means that more energy must be
diverted merely to secure the same amount as before.
But there is no single balance sheet where you see ‘more energy used
to get energy’. Remember that when energy becomes more expensive in real
terms, the system does not absorb that cost at a single point. So
instead of a clear signal ‘we pay this much more for energy’, you get:
‘everything else works slightly worse’. Who in Europe today would
dispute the categorization that everything is a bit worse (although
there are many other reasons for this too)?
How Europe obsesses over prices and thinks little of system-level costs
Bloomberg remarked in an article
from December 2025 that the return of cheaper gas (compared with crisis
levels) had not solved Europe’s energy crisis. It framed the issue as
prices being almost back to normal but competitiveness still declining.
The headline fact – gas prices in Europe had fallen to around €27/MWh –
looks like vindication of the monetary framing. Prices have “normalized.” But normalized relative to what physical reality?
The
article slips in a mention of a very revealing fact: European
consumption is about 20% lower than pre-2022 levels. This is nothing
more than demand destruction masquerading as stability. Europe’s
marginal supply is now LNG, not pipeline gas, and LNG is structurally
more energy-intensive. Meanwhile, costs have been socialized, capital
has been written off, and, most tellingly, demand has been destroyed.
So
rather than a return to normal, system-level surplus energy is
collapsing, which leads to industry restructuring, relocating, or simply
contracting. Demand falls accordingly. Prices then come down because
the energy-intensive parts of the economy are gone. And of course this
is a classic example of closing the barn door after the horse escapes.
Prices might have come down but industry isn’t coming back.
The
monetary system did exactly what it’s good at, but it still couldn’t fix
the underlying problem. Giants such as BASF, Dow, and Thyssenkrupp are
not threatening to leave, but are already gone or half-gone.
What Bloomberg treats as a conundrum (maybe prices haven’t fallen enough or policy adjustments haven’t yet “worked”)
is really just the outcome of declining surplus energy. The article
treats competitiveness as the ultimate frame, whereas competitiveness
itself is actually just downstream of energy surplus. From a
surplus-energy perspective, Europe isn’t losing because it has chosen
the wrong incentives or failed to fine-tune prices, but because its
energy system now absorbs a larger share of economic output just to
sustain itself.
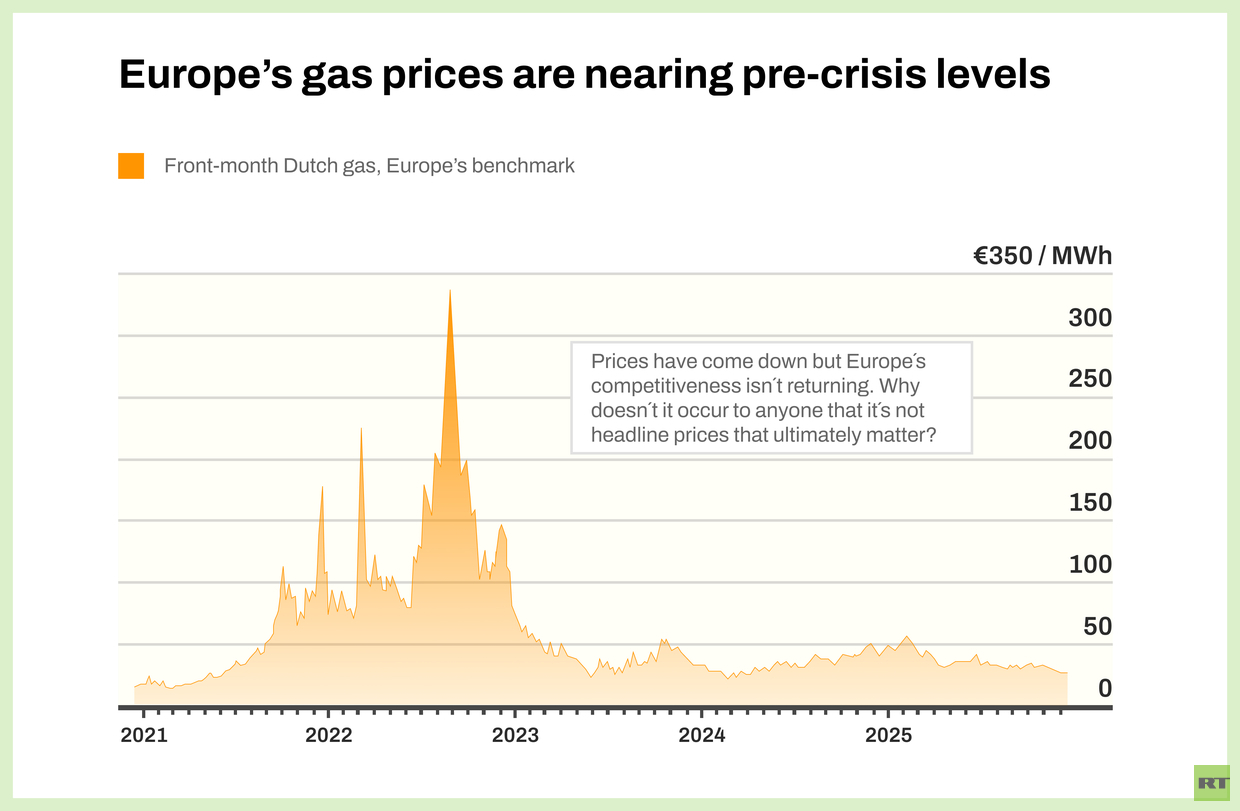
RT based on Bloomberg © RT
For a further look into Europe’s assumptions in action, it is worth examining a policy brief
issued in late 2024 by the prestigious economic think tank Bruegel. The
document, though dry and technical, is fascinating because it maps
almost perfectly onto the flawed energy paradigm described above.
The
argument the brief advances is straightforward: the extreme electricity
prices of 2022 were an aberration, and as renewables expand and gas
recedes from the mix, electricity prices in Europe should fall. At the
center of the analysis is a simple and rarely examined premise: falling
wholesale prices are evidence that the system itself is becoming
cheaper. This premise underpins much of the thinking around the green
energy transition.
Yet the brief itself carefully – and entirely
unwittingly – documents the mechanisms that sever prices from
system-level costs. It explicitly notes that as renewables expand, gas
use declines and marginal generation costs fall, while the fixed-cost
share of the system rises. So even if marginal costs fall, total
obligations do not.
The paper is also candid that the cost of supporting renewables will be “mediated through the state and recovered from consumer bills through levies and charges.”
These costs do not disappear but are simply removed from headline
prices. Likewise, the brief emphasizes that network costs (grid
expansion, cross-border interconnectors, offshore wind integration,
smart meters) are inflationary. These are capital-intensive,
energy-intensive, maintenance-heavy, and sit entirely outside the
wholesale price.
The brief further acknowledges, almost in
passing, extensive cost redistribution: price caps, consumer shielding,
industrial subsidies, cross-subsidization, and fiscal intervention to
smooth outcomes. Of course, once prices are mediated at this scale, they
no longer convey scarcity, and affordability ceases to reflect cost.
Yet, despite all of this – and here the blind spot is clearest – the
brief continues to speak as though “prices coming down” is still a meaningful indicator of underlying improvement. This contradiction runs through the analysis.
Notably,
the author never clearly states that overall system-level costs will
decline. He does not demonstrate it and shows little interest in doing
so. The analysis is profoundly blind to the question of surplus energy.
As Thomas Kuhn observed, a paradigm does not merely shape answers but
determines which questions may remember to be asked. The prevailing
paradigm permits only two: will prices come down, and how will the costs
be shared? The more relevant question – largely excluded – is how much
of Europe’s economic capacity must now be devoted to securing energy.
A civilizational marker
The
proliferation of subsidies, price caps, regulations, and credit lines
does not make energy cheaper. It does not turn a less efficient energy
source into a more efficient one. It merely redistributes claims on
surplus energy or delays recognition of its decline. Running through the
Bruegel document is a quiet, unspoken belief that Europe can design its
way out of material disadvantage and overcome any constraint.
This
belief in the power of sufficiently sophisticated administration is the
sacral core – such as there is one – of the European Union. This
confidence dovetails neatly with a belief that economic problems are
really just monetary problems.
But, as we have demonstrated, the
economy is not merely a monetary system in which physical constraints
can be banished by the royal touch of policy. There is no amount of
shuffling around of financial claims and no clever configuration of
policies that will overcome the cold, hard laws of thermodynamics.
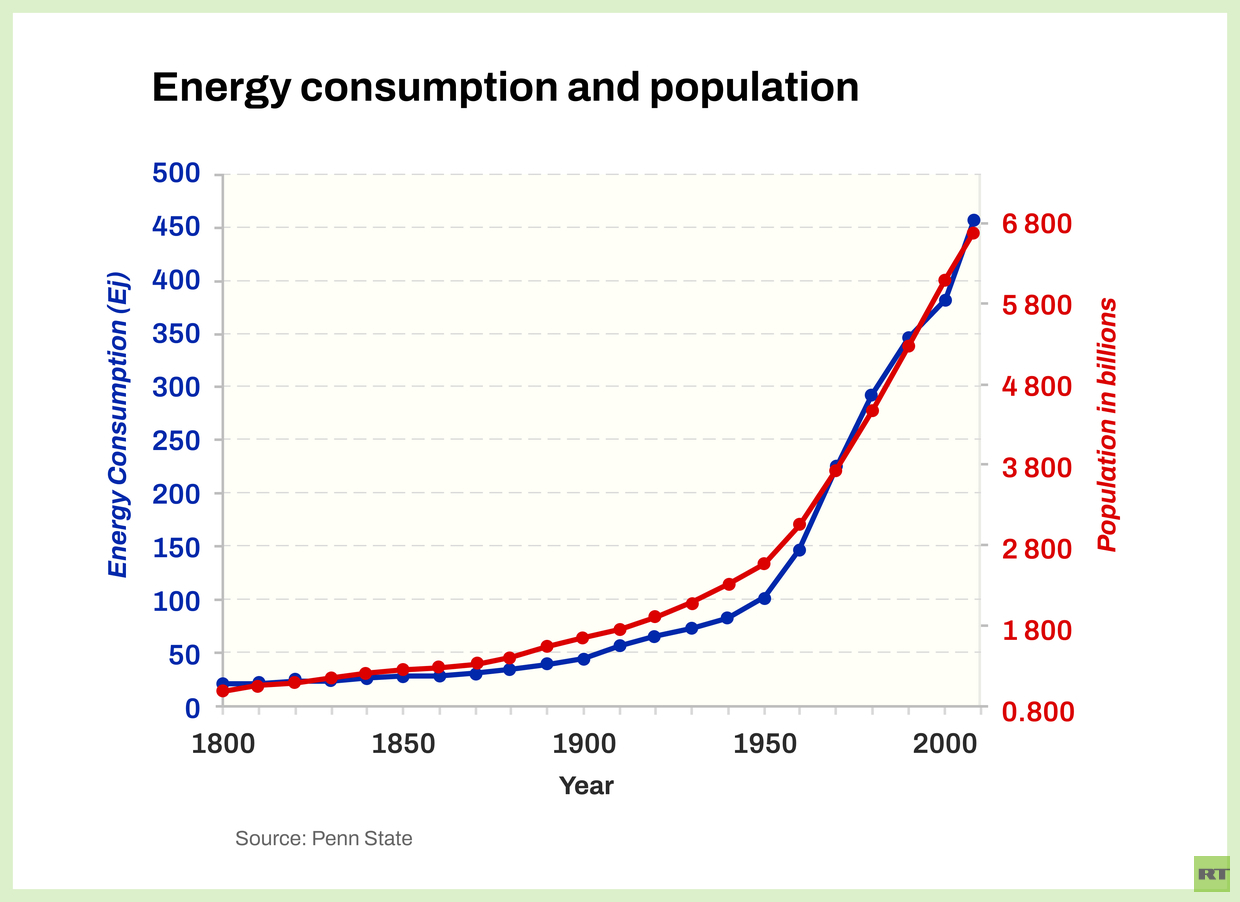
RT based on Penn State University © RT
That
the economy is ultimately an energy system would be painfully obvious
were it not a civilizational blind spot. For those in doubt, plot world
population and total energy consumption on the same time axis from the
Neolithic Revolution onward and see if the two curves can be
distinguished. Population growth is an energy phenomenon before it is an
economic one. Energy is foundational; finance is derivative.
Vaclav
Smil, in his seminal work ‘Energy and Civilization’, argues that every
historically successful energy transition delivered net advantages in
energy density and system-level productivity. It is precisely this
system-level productivity that Europe fails to confront. Doing so would
require acknowledging hard constraints and, by extension, the impotence
of the high priests of Brussels in the face of them.
Far from
solving any of these problems, Europe's sprawling administrative state
is itself devouring ever more amounts of surplus energy. Joseph Tainter,
well known for his treatise ‘The Collapse of Complex Societies’, warned
about the declining marginal returns of rising complexity and of taking
short-term gains at the price of long-term fragility. In Europe’s case,
the complexity of the solutions is astounding but even the short-term
gains are pretty paltry.
https://www.rt.com/op-ed/authors/henry-johnston/
By Henry Johnston, a Moscow-based writer who worked in finance for over a decade
https://www.rt.com/op-ed/authors/henry-johnston/