Alex Krainer
As I discussed in yesterday’s report, ECB President Christine Lagarde’s
remarks during the 62nd Munich Security Conference should have come as a
cold shower for the capital markets. Only two months ago, Lagarde was warning that Europe was facing an “existential crisis,” and called for urgent reforms.
In
Munich, she expressed doubts about European economy’s competitiveness
and again warned about financial instability that lies ahead:
The
ECB needs to be prepared for a more volatile environment. … We must
avoid a situation where that stress triggers fire sales of
euro-denominated securities in global funding markets…
Then on 18 February, only four days after that speech, the FT reported that
Ms. Lagarde is planning to step down from the ECB, well before her term
ends in October 2027. Who steps down early from such a privileged
sinecure? Ms. Lagarde does not have grandchildren with whom she’d prefer
to spend time. The obvious suspicion is that she knows that the “more
volatile environment” may be coming quite soon and prefers to go while
the going is good.
The fact that Europe’s economy is in a
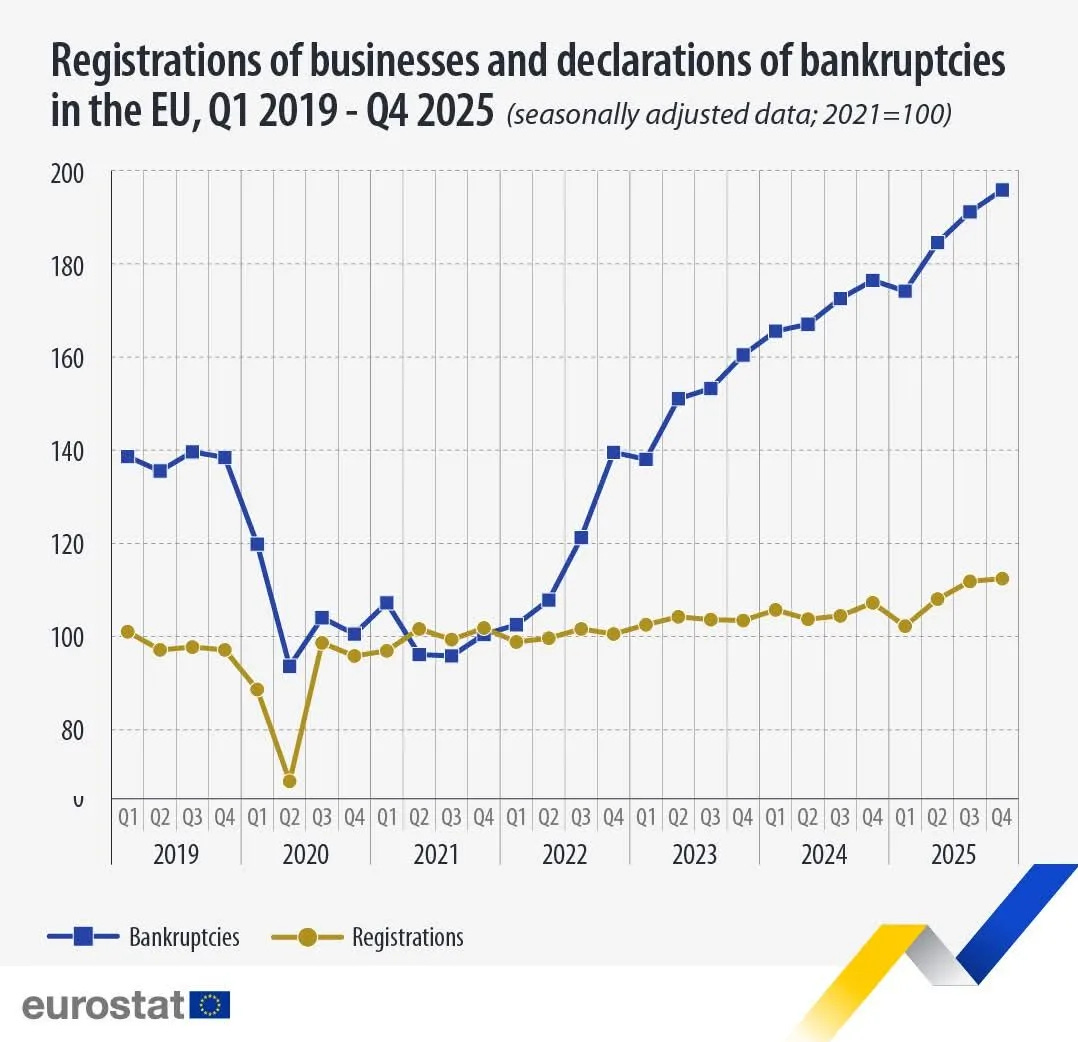
structural decline is not news. The following chart tells the story in
two important aggregates: the number of companies going out of business
vs. the number of new companies being formed:
The
trends are obviously quite dismal and only getting worse. While new
business registrations are basically flatlining, bankruptcies are
soaring. That’s Europe’s tax base falling off a cliff taking jobs along
with it. And even if the markets aren’t registering these trends in the
near term, it’s clear that on the longer horizon, the weakness of
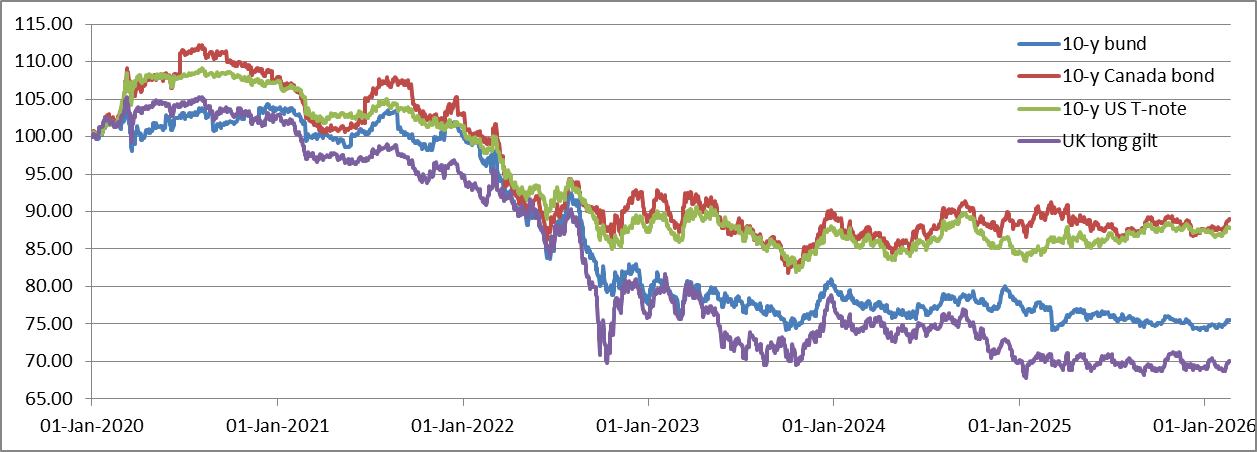
European economies is showing. The chart below shows the price of the
U.S., Canada’s, Britain’s and Germany’s 10-year government bonds:
Again,
we can see that the British debt is the weak link, but Germany is not
doing much better. In this sense, Germany is something of a benchmark,
since it’s still perceived as the safest European
economy. Meanwhile, it’s interesting to note that the U.S. and resource
rich Canada have clearly diverged from European economies, even if their
performance has been merely flat. Given the dismal conditions in the
bonds markets, flat may be the new bullish.