Real world oil prices are far higher than the figures seen on TV news reports
Gas prices over $6.00 are displayed at a Shell station across from the Marathon Petroleum Corp's Los Angeles Refinery in Carson, California, April 2, 2026 © Getty Images; Justin Sullivan
When
the first US and Israeli missiles hit Iran more than a month ago, an
oil price of $150 per barrel was considered a doomsday prediction. But
the price of physical Brent crude is already a hair’s breadth from $150,
while the futures price hasn’t caught up yet.
The Brent
front-month futures price – which serves as a barometer for 80% of the
world’s crude oil – has sat above $100 per barrel for several weeks.
Rising and falling as US President Donald Trump changes the war’s aims
and end date, it closed above $109 on Thursday, already higher than at
any point since the Ukraine conflict escalated in early 2022.
But
to understand just how severe the current crisis is becoming, it’s
important to look at the Dated Brent price. Only widely monitored during
times of market disruption, this represents the actual on-the-spot
price that purchasers are paying for Brent cargoes in the North Sea. On
Thursday, it reached $141.37, a level unseen since the onset of the 2008
financial crisis.
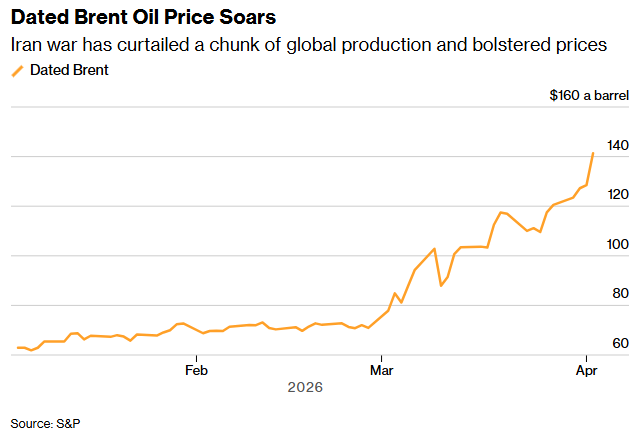
Dated Brent oil prices pass $141 per barrel, April 3, 2026 © S&P
This speaks to a severe supply
shortage on the ground as buyers are willing to pay a huge premium to
get their hands on barrels, not in the near future, but right now.
What is the significance of the huge spread?
What newspapers and broadcasters typically show is the front-month
Brent price: bought by traders for delivery on a specific date the
following month. This is the most liquid and widely quoted benchmark.
Importantly, pricing reflects future expectations, so in this case
investors are betting on at least some kind of deescalation and
denouement in the Persian Gulf.
The front-month is also the
domain of speculators who have no intention of ever receiving any oil:
instead they seek to take advantage of price shifts and exit their
positions before delivery. The front-month price does of course reflect
physical realities – but it’s also somewhat financialized.
The
fact that actual physical Brent crude is moving at prices $32 higher
than the front-month indicates that the physical supply of oil is
extremely tight. Typically, the spread between the front-month contract
and Dated Brent is less than $2, although in a tight market it can drift
somewhat higher. What we are seeing now is highly abnormal. This higher
Dated Brent price isn’t the result of hedge funds or momentum traders
bidding up the price. This is what is changing hands on the ground for
real barrels.
The epicenter of the crisis is the Strait of
Hormuz. A lot depends on what happens in this chokepoint. Less than 40km
wide at its narrowest point, just under a third of the world’s seaborne
oil transits the strait on its way from Middle Eastern producers to
global markets.
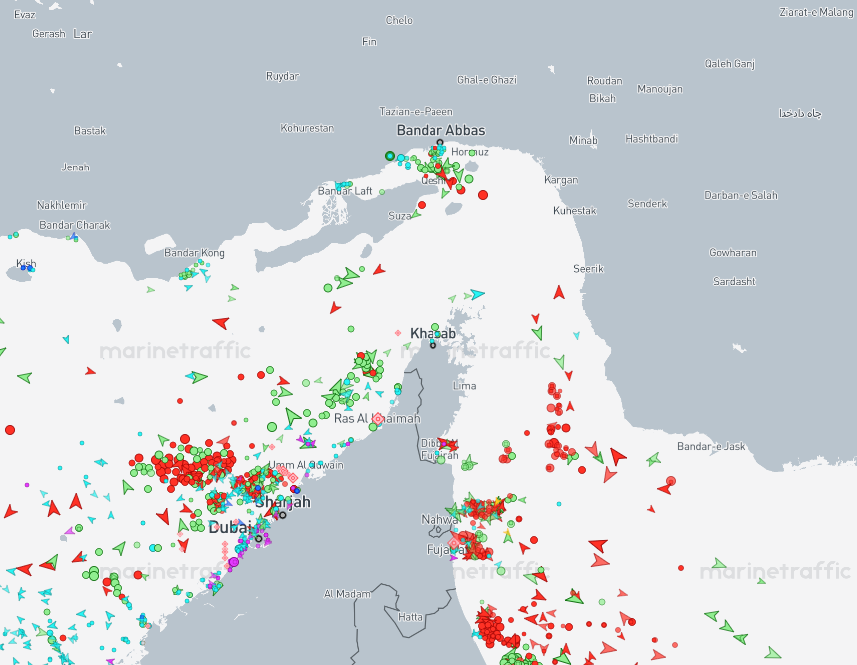
Marine traffic backed up on either side of the Strait of Hormuz, April 3, 2026 © MarineTraffic
Once a free
international waterway, the strait has been turned into a de-facto toll
road overseen by the Iranian military. Iran’s Islamic Revolutionary
Guard Corps (IRGC) decides which vessels are allowed through, with
limited numbers of Chinese, Indian, Pakistani, and South African ships
making the passage in recent weeks. Daily transits have fallen from
around 130 before the war, to low single figures last month, and around a
dozen this week.
Why isn’t front-month Brent trading closer to the spot market?
Based
on the price difference, the Brent futures market is still relatively
sanguine about the prospects for a resolution. Some analysts, however,
believe the market isn’t fully reckoning with the supply shortage that
is now driving spot prices through the roof. There is also the typical
internet chatter about the futures market being manipulated to keep some
kind of lid on oil prices. In other words, the big spread is garnering a
lot of attention.
Meanwhile, there is no sign that normal traffic will resume in the
Strait of Hormuz anytime soon. US President Donald Trump has swung
between declaring the passage open, telling shipping companies to “have courage”
and sail through it regardless, vowing that the US will open it, and
telling his allies to deal with the closure themselves. The messaging,
and Trump’s timeline for an end to the conflict, changes day by day.
Looking
at other benchmarks, there are signs of a deepening crisis. Dubai and
Omani oil is now selling for well above $150, reflecting the difficulty
these Gulf nations have in exporting their product, while West Texas
Intermediate (WTI) – priced in landlocked Oklahoma – surpassed Brent by
$3 on Thursday. This indicates that traders predict further
uncertainties with the supply of seaborne Brent, and are pivoting toward
American crude instead.
Additionally, the WTI crude prompt
spread (price difference between the two nearest contracts) widened to
more than $16 per barrel on Thursday, the largest premium on record.
This type of widening spread is often due to short-sellers who had bet
on a price drop (in this case due to a quick end to the war) getting
squeezed and buying back contracts to close their positions, in turn
driving up front-month prices.
How high will oil go?
The
vast spread between what hedge fund traders see on their Bloomberg
terminals and what buyers are paying right now is a glaring red flag,
suggesting a massive supply crunch. Physical oil prices are closing in
on the psychological barrier of $150, and analysts have readjusted their
worst case scenario predictions, with CNN declaring on Thursday that
should the conflict drag on until June, a front-month price of $200 “isn’t as crazy as it sounds.” Left unsaid is the fact that at a front-month price of $200, the spot price would almost certainly be even higher.
Zooming
out from Brent and WTI, there are dozens of different oil prices,
representing more than 100 different blends of crude, their spot prices,
and their varying futures contracts. All are higher than they were in
February, and for the average person around the world the result is the
same: the war on Iran has made fuel, food, and basic necessities more
expensive, and life tougher.
“Global recession is already inevitable this year, with energy-importing countries being hit the hardest,” Russian presidential envoy Kirill Dmitriev warned on Thursday. “This will become clear to many by June.”
By RT newsroom, a team of multi-lingual journalists with over a decade of experience in Russian and international reporting, delivering original research and insights often missing from mainstream coverage
https://www.rt.com/op-ed/authors/rt-newsroom/