Thousands of New Zealand first-home buyers are confronting the painful aftermath of the housing boom, with properties purchased near the market peak now worth less than the mortgages secured against them. While economists say negative equity is generally manageable for borrowers who can continue making repayments, it can leave households effectively trapped — unable to sell, relocate or access the equity they expected their home to build.
eLocal Report: Based on reporting by Susan Edmunds, Money Correspondent for RNZ, HERE.
New Zealand's long housing downturn has left thousands of recent first-home buyers owing more on their mortgages than their properties are now worth, with those who entered the market near its 2021–22 peak particularly exposed.
Cotality chief economist Kelvin Davidson estimates that about 3600 households nationwide are currently in negative equity, assuming those buyers originally purchased with a 20 percent deposit.
But that assumption means the true number is likely to be higher.
Many first-home buyers entered the market with deposits considerably below 20 percent. Cotality estimates about 29,000 first-home buyers purchased properties during the 18 months around the market peak, and a large proportion of those homes would still be worth less today than their buyers originally paid.
The renewed pressure comes as borrowers are also confronting rising interest rates following the Reserve Bank's latest increase in the Official Cash Rate.
House Prices Still Well Below the Peak
The scale of the problem reflects just how far New Zealand's housing market has fallen.
National house prices remain approximately 17 percent below their previous peak, according to the RNZ report, while Auckland and Wellington remain more than 20 percent below peak levels.
The experience has not been uniform across the country. Canterbury and Otago, for example, have recovered to around their previous peaks.
But for people who bought in some of the country's most expensive markets during 2021 and early 2022, the combination of falling property values and large mortgages has created an uncomfortable financial reality.
Their mortgage may be gradually shrinking, but the asset securing it has fallen even faster.
‘We've Lost Half Our Deposit’
RNZ highlighted anonymous accounts from recent buyers describing what the downturn has meant personally.
One homeowner separating from their partner said their townhouse's capital value was $100,000 below its purchase price, raising the prospect of remaining in debt even after selling.
Another buyer who purchased in 2023 — after the market peak — said their property's value had fallen by $80,000.
Once an estimated $35,000 real estate agent fee was included, the buyer calculated that half of their original deposit had effectively disappeared.
Another homeowner who bought at the 2021 peak estimated their property had lost at least $200,000 in value and described the purchase as a financial mistake that continued to hurt years later.
Others told of being stuck in townhouses or apartments longer than intended because selling would crystallise their losses.
Negative Equity Doesn't Mean the Bank Comes Knocking
Despite the alarming numbers, economists and mortgage specialists emphasise an important distinction.
Negative equity is not necessarily a crisis for a household that can continue meeting its mortgage payments.
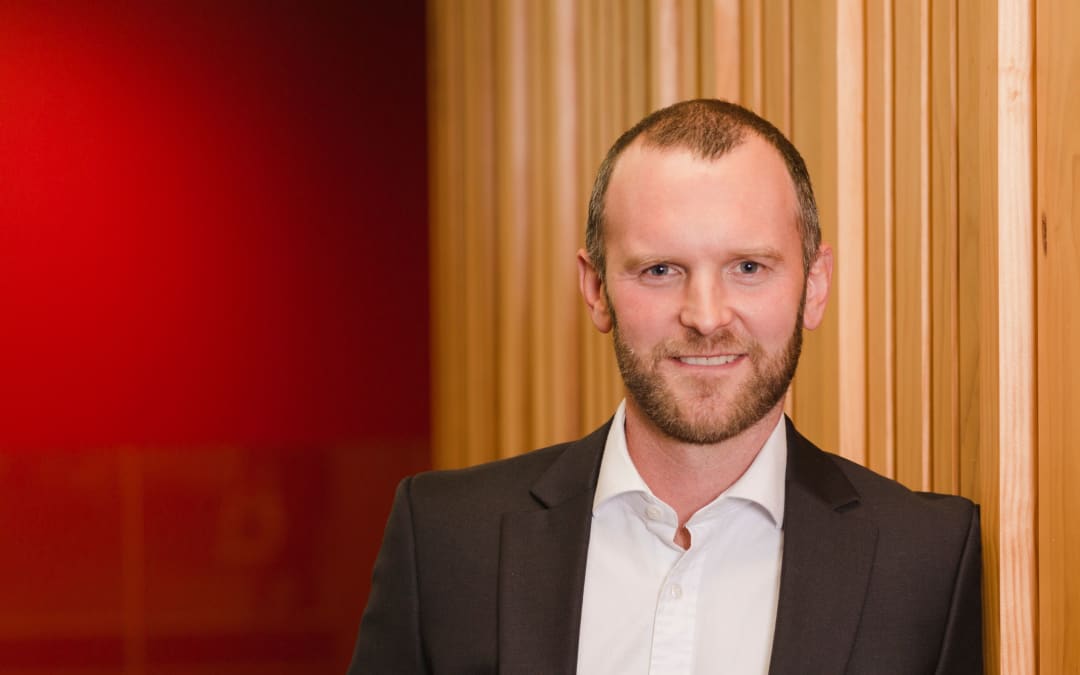
Cotality chief economist Kelvin Davidson. Photo: Supplied
Davidson said his calculations assumed borrowers had not substantially reduced their mortgage principal since purchasing.
That is normal during the early years of a table mortgage because a relatively large proportion of each repayment goes towards interest rather than reducing the principal.
Although being in negative equity can be psychologically difficult, Davidson said it does not automatically create a problem between the borrower and lender.
As long as repayments continue, the bank generally has no reason to intervene simply because the property's market value has fallen.
That is supported by the current performance of New Zealand's mortgage book, with Davidson noting there are very few non-performing housing loans.
The Real Problem Comes When You Need to Sell
Negative equity becomes much more serious when circumstances force a homeowner to move.
A job opportunity in another region, relationship separation, financial hardship or a growing family needing a larger home can turn what was previously only a paper loss into a real financial constraint.
If a property sells for less than the outstanding mortgage, the homeowner can potentially be left owing money after the house itself is gone.
New Zealand Financial Services Group chief executive Bruce Patten said this was the primary problem confronting borrowers caught in negative equity.
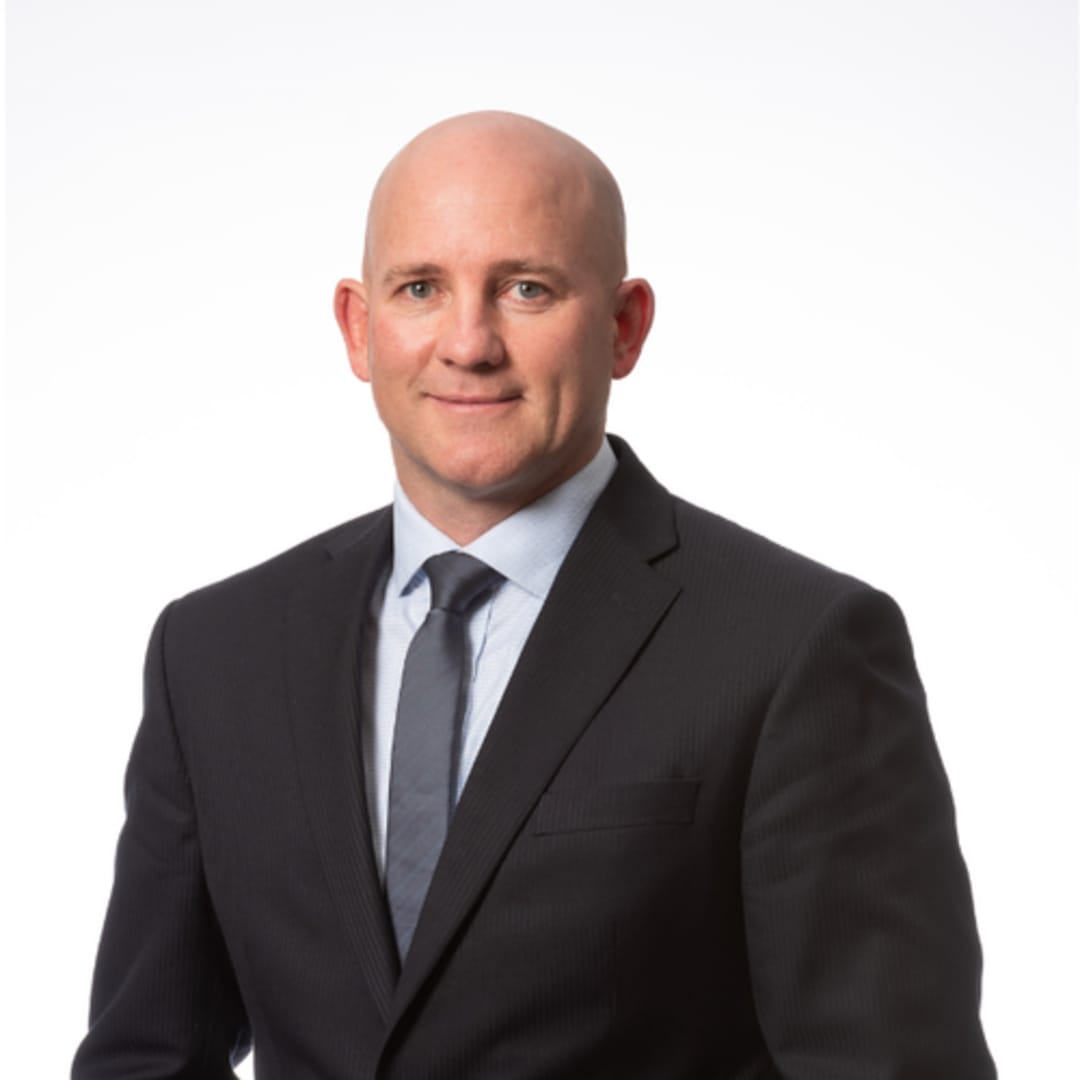
New Zealand Financial Services Group chief executive Bruce Patten. Photo: Supplied / NZFSG
Patten's recommendation for borrowers who have the option is straightforward: remain in the property and allow time for the market and mortgage balance to improve.
He noted that New Zealand has so far avoided a repeat of conditions during the Global Financial Crisis, when mortgagee sales sometimes resulted in people losing their properties while still being left with personal debt.
For borrowers experiencing financial difficulty, Patten recommended contacting their adviser rather than waiting until repayments become unmanageable. Options can sometimes include interest-only arrangements or temporary repayment holidays.
Rising Interest Rates Add Another Problem
The timing is particularly uncomfortable because mortgage rates are again facing upward pressure.
Kiwibank chief economist Jarrod Kerr told RNZ that rising interest rates on top of cost-of-living pressures would make conditions more difficult for affected households.
Kerr has personal experience of a housing downturn. He bought his first home in 2007 before its value fell and took years to recover.
His observation points to an aspect of housing downturns that headline price indices cannot easily measure: the psychological effect of watching years of savings apparently disappear.
For a first-home buyer who spent years assembling a deposit, seeing $80,000, $100,000 or $200,000 disappear from the theoretical value of a property can fundamentally alter perceptions of financial security — even if mortgage payments remain affordable.
Keep Paying Down the Loan
Mortgage adviser Campbell Hastie offered similar practical advice: borrowers who can meet their repayments should continue doing so and avoid becoming consumed by short-term estimates of their home's value.
Every principal payment gradually improves the homeowner's equity position regardless of what the wider market is doing.
There can, however, be another complication for people who originally purchased with less than a 20 percent deposit.
Those borrowers may be paying a low-equity premium on top of their mortgage interest rate. When their loan comes up for refixing, an adviser can examine whether their equity position has improved enough for that additional cost to be removed.
The crucial point is that falling house prices do not change the borrower's contractual obligation.
If the mortgage continues to be serviced, the loan balance continues to decline.
A Personal Crisis Rather Than an Economic One?
Otago University economist Murat Ungor argues the distinction between household hardship and national economic impact is important.
For the estimated 3600 households, he told RNZ, negative equity is real and painful.
But he described it primarily as a balance-sheet problem rather than a cash-flow problem for borrowers who remain capable of servicing their mortgages.
The more significant restriction is mobility.
Someone in negative equity may be unable to sell their home to relocate for a better job. A business owner may also have less home equity available as collateral for borrowing.
Those circumstances can produce genuine individual lost opportunities.
At a national level, however, Ungor believes the number of households involved remains too small for negative equity itself to become a significant drag on investment or the wider economy.
Does This Affect New Zealand?
Yes — because behind the relatively small national percentage sits a much larger question about the consequences of New Zealand's extraordinary housing cycle.
Thousands of first-home buyers entered the market when prices were close to historic highs, often after being told that getting onto the property ladder was the essential first step towards long-term financial security.
Many borrowed heavily to do it.
Those who bought near the peak have subsequently experienced one of New Zealand's deepest property downturns in decades. Now, just as some households might have expected lower borrowing costs to provide relief, interest rates are moving upward again.
For homeowners who do not need to sell, negative equity may ultimately prove temporary. Mortgage balances decline over time and property prices may eventually recover.
But that does not mean there is no cost.
A household unable to move for a new job, upgrade for a growing family, separate cleanly after a relationship breakdown or use home equity to finance a business is experiencing a very real restriction on its economic choices.
And there is another uncomfortable lesson.
For decades, New Zealanders have been encouraged to regard residential property not simply as somewhere to live, but as one of the country's most dependable mechanisms for accumulating wealth.
For thousands who bought near the top of the market, the experience has demonstrated something easily forgotten during a property boom:
a house may be a home and a long-term asset — but its value can fall while the debt remains very real.
Source: Susan Edmunds, RNZ — ‘We've lost half our deposit’: About 4000 first-home buyers owe more than their homes worth. Original RNZ images, captions, credits and relevant source links retained.
Independent reporting. Original context. Credited sources.